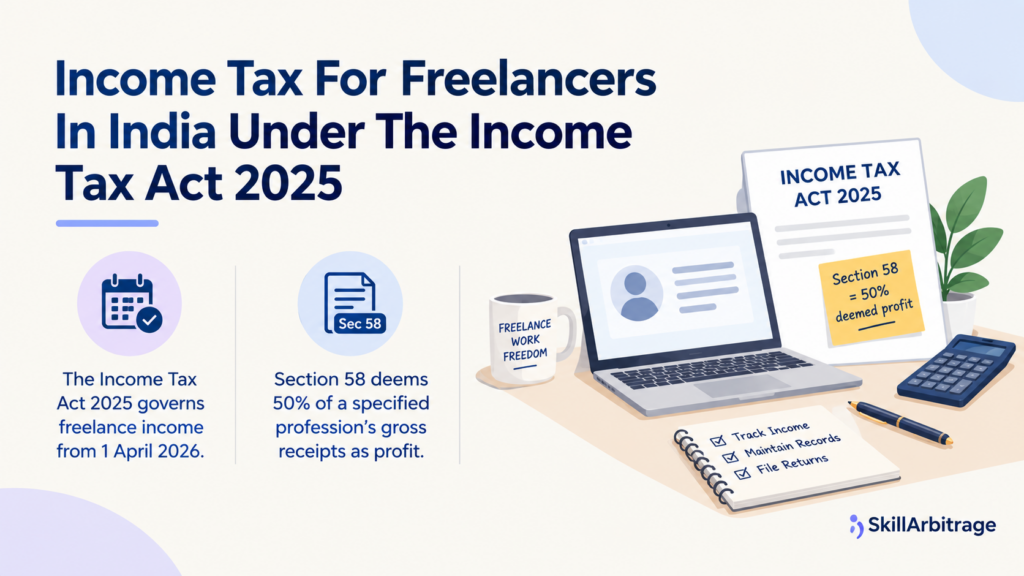

Income tax for freelancers in India under the Income Tax Act 2025 works on income earned from 1 April 2026 onward, and not on the return most freelancers are filing right now. The Act came into force on that date under section 1(3), repealed the Income-tax Act, 1961 under section 536, and governs what the statute now calls tax year 2026-27. The presumptive scheme that everyone still calls section 44ADA is section 58(2), Table Sl. No. 3, and it deems 50% of gross receipts to be profit for a specified profession earning up to Rs 50 lakh, or up to Rs 75 lakh where cash receipts stay within 5%. A non-audit return for that year falls due on 31 July 2027.
Assessment year and previous year are gone, replaced by a single tax year defined in section 3, and the change is not cosmetic. In the Income Tax Department’s own utility comparing the two statutes, the entry for section 2(9) of the old Act, “Assessment year”, returns a blank against the 2025 column. There is no successor provision, so a freelancer converting older advice has to convert the calendar as well as the section numbers.
The renumbering runs deep enough that a section number now dates a page. Every deduction-at-source provision of the 1961 Act, including 194J for professional fees, 194-O for platform payments and 194M for payments by individuals, collapsed into a single section 393. A page citing section 194J in late 2026 is not quoting an outdated rule. It is quoting a provision that no longer exists.
Which year the Income Tax Act 2025 applies to
The Income Tax Act 2025 applies to tax year 2026-27 onward, which means income earned on or after 1 April 2026. Section 1(3) is unambiguous about the start date: “Save as otherwise provided in this Act, it shall come into force on the 1st April, 2026.” The Act received assent on 21 August 2025 as Act No. 30 of 2025, so there was a gap of more than seven months between enactment and commencement.
Section 3(1) then replaces two old concepts with one. It reads: “For the purposes of this Act, ‘tax year’ means the twelve months period of the financial year commencing on the 1st April.” Tax year 2026-27 therefore runs from 1 April 2026 to 31 March 2027, and it is the year the income is earned. Nothing is assessed in a separate later year carrying its own label.
Section 3(2) covers the case that applies to a large share of new freelancers. Where a profession is newly set up during a financial year, the tax year begins on the date it is set up and ends with that financial year. A freelancer who registered a practice in October 2026 has a tax year of roughly six months, not a pro-rated twelve.
Section 536(1) disposes of the old statute in nine words: “The Income-tax Act, 1961 (43 of 1961) is hereby repealed.” What follows in section 536(2) matters more than the repeal itself. Twenty-two savings clauses keep the 1961 Act operative for everything that belongs to an earlier year, and clause (c) preserves it for any proceeding relating to a tax year beginning before 1 April 2026.
That saving produces the situation every Indian freelancer is in during the second half of 2026, and almost no published guidance acknowledges it. A return filed now covers financial year 2025-26 and is governed by the repealed Act, with its old section numbers intact. At the same moment, the same freelancer is accruing liability for tax year 2026-27 under the new Act and will pay advance tax on it under section 408.
The practical consequence is that the correct section number depends on which year is being discussed, and a guide that does not say which year it means is not usable. Advance tax paid in December 2026 is governed by the 2025 Act. The return filed alongside it is governed by the 1961 Act. Both statements are true on the same day.
The department published a comparison utility precisely because of this, letting a reader enter an old section and see its successor. That utility is also where the clearest evidence of the abolished assessment year sits, since the tool returns a successor for almost every provision and a blank for section 2(9).
The Central Board of Direct Taxes has also published transition guidance of its own, in a set of frequently asked questions on the interplay between the two statutes and a separate set on the savings in section 536. Both sit on the department’s Income-tax Act, 2025 page alongside the bare Act and the rules. A freelancer working through an unusual carry-over, such as a loss brought forward from an earlier year or a proceeding still open, has an official starting point rather than commentary.
The overlap is temporary, which is worth saying plainly because it changes how long old material stays dangerous. Once the return for tax year 2026-27 is filed in 2027, only one statute is in play for current compliance, and the 1961 Act recedes to whatever remains open from earlier years. Until then, the safest habit is to check which year a figure belongs to before checking whether the figure is right.
As enacted, the Act runs to 536 sections across 23 chapters with 16 schedules. The department’s live section browser currently reports 553 sections for the Act as amended by the Finance Act, 2026, and the reason for the difference is not documented, so the enacted figure is the safer one to work from. Either way the drafting is visibly more compact than the statute it replaced, achieved largely by replacing long strings of provisos with tables, which is why so many familiar rules now appear as a row in a table rather than as a section of their own.
One structural point is routinely misreported. Rates of tax are not now housed in the Act. Section 4(1) preserves the old architecture exactly: “Where any Central Act enacts that income-tax shall be charged for any tax year at any rate or rates, income-tax for such tax year shall be charged at that rate or those rates.” Surcharge, cess and the rates in force still arrive through the annual Finance Act.
The exception is the default personal regime, whose slab table sits inside the statute at section 202. That single inconsistency is why some commentary claims rates moved into the Act and other commentary claims they did not. Both are describing a different half of the same arrangement.
Specified profession or business
Whether a freelancer carries on a specified profession decides which rules apply to them, and it is settled by a closed list in section 62(4) rather than by how the work is described on an invoice. The provision reads: “‘specified profession’ means (a) legal, medical, engineering, architectural, accountancy, technical consultancy, interior decoration, information technology or company secretary; or (b) any other profession, as may be notified by the Board in this behalf.”
Two things about that list differ from its predecessor. Information technology and company secretary now appear in the statute itself, where under section 44AA(1) of the old Act the enumerated list stopped at interior decoration and those two categories arrived only through Board notification. Film artist and authorised representative, both notified categories under the old regime, are not named in the new text. Whether they survive through the notification power in clause (b) is not established, and this article does not assume that they do.
The section 62(4) answer decides three separate things further down, which is why it has to be settled before any computation begins.
It decides which presumptive row is available. Section 58(11)(a)(iii) defines an “eligible assessee” for the 6% and 8% business scheme as someone who “does not carry on specified profession as defined in section 62(4)”. A freelance software developer is therefore shut out of the business row completely, and is pushed onto the 50% professional row whether or not that produces a lower figure.
It decides the books threshold. Under section 62(1)(a), any person carrying on a specified profession must keep books of account, with no monetary floor attached. Everyone else gets the thresholds in section 62(2), and for an individual those are modified by clause (d) to income above Rs 2,50,000 or turnover above Rs 25 lakh.
A developer billing Rs 6 lakh is inside the books requirement. A video editor billing the same amount is not.
It decides whether the five-year lock-out in section 58(7) can ever apply, a point taken up in the next section.
Reading the list against the trades SkillArbitrage readers actually work in produces a clean split on the statutory words, and a genuinely unsettled area beyond them.
Inside the list, without argument: a freelance software developer or data engineer, on “information technology”; a freelance bookkeeper or accountant, on “accountancy”; a freelance engineer, architect, lawyer or company secretary, on their own named entries. A freelance management consultant will usually fall under “technical consultancy”, though that phrase has generated litigation for decades and the fit depends on the work rather than the job title.
Not named in the list: content writers, video editors, graphic designers, social media managers, translators and search marketing consultants. On the statutory wording those trades sit in the business row of section 58, computing at 6% or 8% rather than 50%, with a ceiling of Rs 2 crore rather than Rs 50 lakh. For a freelancer with low costs that is a dramatically better outcome, which is exactly why the question is contested.
And contested is the honest word. The same question runs across a dozen practitioner threads on Indian tax forums, asked by graphic designers, web developers, translators, journalists and search consultants, with chartered accountants openly disagreeing with each other inside a single thread. Commercial guides tend to reproduce the notified list and stop, without adjudicating any of the trades their readers actually work in.
A freelancer whose trade is not named should treat the classification as a question for their own adviser rather than a settled matter, because the two rows produce different deemed profits, different ceilings and different lock-out consequences. The rate a freelancer charges does not enter the test at all, though it obviously decides which ceiling bites first, and figures for one such unnamed trade are set out in our look at what search marketing freelancers charge in India.
Two further eligibility conditions sit alongside the trade question, and both are easy to miss because they are buried in definitions rather than stated as rules. Section 58(11)(b) defines a “specified assessee” for the professional row as “an individual or a firm, other than a limited liability partnership, who is a resident in India”. The parallel definition of “eligible assessee” for the business row covers an individual, a Hindu undivided family or a firm other than a limited liability partnership, again resident in India.
So a Hindu undivided family may use the business row and may not use the professional row, and a limited liability partnership is shut out of both. Residence is required either way, which makes it the second half of the same eligibility question rather than a separate cross-border topic. A freelancer who is not resident in a given tax year cannot use either row, whatever their trade.
Section 6 supplies the tests, and they are the familiar ones. An individual is resident under section 6(2)(a) on 182 days or more in India during the tax year, or under 6(2)(b) on 60 days in the year combined with 365 days across the preceding four. Sections 6(4) and 6(5) stretch that 60-day test to 120 days for a visiting citizen or person of Indian origin whose Indian income exceeds Rs 15 lakh, and section 6(7) deems an Indian citizen resident where they are not liable to tax anywhere else and have Indian income above the same figure.
The provision that catches travelling freelancers is section 6(14). It defines “income from foreign sources” to exclude income derived from “a business controlled in or a profession set up in India”. A practice established in India does not become foreign-source income because its owner has moved abroad for a season, which is a distinction worth settling before booking a long stay, and one explored further in our piece on whether Indian tax applies on a digital nomad visa.
Computing income tax for freelancers under the Income Tax Act 2025
Computing income tax for freelancers under the Income Tax Act 2025 runs through one of two routes: a presumptive figure under section 58, or actual profit after expenses under sections 26 to 36. The section 62(4) answer from the previous stage decides which version of the presumptive route is even on the table, so the order matters.
The presumptive route under section 58
Section 58 is a single consolidated provision carrying a three-row table, and that consolidation is the reason old advice misdirects. Row 1 holds the business scheme that used to be section 44AD, row 2 the goods carriage scheme that used to be section 44AE, and row 3 the professional scheme that used to be section 44ADA. Citing “section 58” without the row is therefore incomplete, because the three rows carry different rates and different ceilings.
For a specified profession, the ceiling in column D of row 3 is expressed as an amount that “(a) Does not exceed fifty lakh rupees; or (b) does not exceed seventy-five lakh rupees, where the amount or aggregate of amounts received in cash does not exceed 5% of the gross receipts.” The old formulation of the higher limit was phrased as 95% of receipts arriving through banking channels. The new one tests the cash side instead, which is the same arithmetic approached from the opposite direction.
Column E is where most published guidance goes wrong. It reads: “50% of the gross receipts or profit claimed to have been actually earned, whichever is higher.” The scheme is not an election to declare half of receipts. It sets a floor.
A consultant with Rs 40 lakh of gross receipts and Rs 6 lakh of genuine costs has actually earned Rs 34 lakh, which is 85% of receipts. Under column E the figure chargeable is Rs 34 lakh, not Rs 20 lakh, because the actual profit is higher than the deemed one. The scheme saves that consultant the bookkeeping, not the tax.
The benefit lands on a different profile entirely: a freelancer whose real costs exceed half of receipts gains nothing, and a freelancer whose costs sit well below half pays on a figure close to their real profit anyway. Where it genuinely helps is the middle case, where costs are real but awkward to evidence, and the deemed figure is defensible without a filing cabinet.
Three mechanical rules attach to anyone inside the scheme. Section 58(9) deems a cheque or bank draft that is not account payee to be cash, so a freelancer relying on the Rs 75 lakh ceiling has to watch how clients pay, not merely whether they pay by instrument. Section 58(4) bars “any loss, allowance or deduction allowable under the provisions of this Act” against presumptive income, which is wider than the old section 44ADA(2) that barred only sections 30 to 38. Section 58(6) treats depreciation as already claimed and allowed, so the written-down value of a laptop falls each year regardless, and it cannot be claimed again on exit.
For the freelancer whose trade is not on the section 62(4) list, row 1 applies instead: a ceiling of Rs 2 crore, or Rs 3 crore on the same 5% cash test, computing at 6% of receipts arriving by specified banking or online mode and 8% of the rest, and once again “whichever is higher” against actual profit.
Sections 58(7) and 58(8) carry a five-year consequence for leaving the scheme, and it is keyed expressly to Table Sl. No. 1. An eligible assessee who declares under the business row and then, within the following five tax years, declares otherwise, loses the benefit of the section for five tax years, and section 58(8) then forces books under section 62 and audit under section 63 once income exceeds the exemption limit.
No equivalent provision attaches to row 3. A specified professional may use the presumptive scheme in one year, claim actual expenses the next, and return to it the year after, without triggering anything. This reproduces the position under the 1961 Act, where section 44AD(4) had no counterpart in section 44ADA, and it is the single most consequential asymmetry between the two rows. Reports that section 58 introduced a general five-year lock-out for freelancers are reading row 1’s rule onto row 3.
One caution for anyone checking this against the bare text. Section 58(7) refers to declaring profit “in contravention of the provisions of sub-section (1)”, where sub-section (1) is the overriding clause and the substantive computation rule sits in sub-section (2). The reference appears to be a drafting slip, which is a reason to paraphrase the provision rather than lift it.
Claiming actual expenses instead
The alternative is ordinary computation, and its central provision survived the rewrite almost untouched. Section 34(1) allows “any expenditure … laid out or expended wholly and exclusively for the purposes of the business or profession”, excluding capital expenditure and “personal expenses of the assessee”. That is the old section 37(1) test, including the personal-expenses bar that decides how much of a home internet connection or a shared laptop a freelancer can actually claim.
Depreciation is section 33, and this is worth stating flatly because a good deal of aggregator commentary has it as section 34. Section 33 governs depreciation; section 34 governs general expenditure. The rate for “computers including computer software” is 40% of written-down value under Appendix I to the Income-tax Rules, 2026, which is headed as being made under rule 25.
Two restrictions in section 33 hit freelancers specifically. Sub-section (4) halves the rate where an asset is acquired during the year and put to use for under 180 days, so a laptop bought in January depreciates at 20% that year rather than 40%. Sub-section (3)(b) restricts an asset used “partly, or not wholly and exclusively” for the profession to “the fair proportionate part thereof as determined by the Assessing Officer”, which is the provision that governs a single machine used for both client work and everything else.
A freelancer buying a Rs 1,20,000 laptop in June 2026 and using it four-fifths for client work claims 40% of Rs 1,20,000, restricted to the four-fifths proportion, giving Rs 38,400 in the first year. The same laptop bought in January 2027 attracts the half-rate rule and yields Rs 19,200.
Two disallowances matter more to solo operators than their profile suggests. Section 36(4) disallows expenditure where payments to one person in one day exceed Rs 10,000 and are not made through specified banking or online mode, which catches cash payments to a subcontractor or a studio. Section 35(b)(i) disallows 30% of a sum payable to a resident where the freelancer was themselves required to deduct tax and did not, allowed back in the year the tax is eventually paid. A freelancer who subcontracts is a deductor as well as a deductee, and the pricing consequences of that are taken up in our guide to pricing bookkeeping services for US clients from India.
Books of account and tax audit
Books and audit are consequences of the two choices above rather than separate decisions. Section 58(3) sets the trigger: a person who claims profits lower than the deemed figure, and whose total income exceeds the maximum amount not chargeable to tax, must keep books under section 62 and get them audited under section 63. There is no monetary floor on that trigger, so a professional with Rs 18 lakh of receipts who declares below 50% is inside it.
Audit thresholds otherwise sit in the table to section 63(1). For a profession the test is gross receipts exceeding Rs 50 lakh in a tax year. For a business it is Rs 1 crore, rising to Rs 10 crore where both cash receipts and cash payments stay within 5% of their respective totals, with section 63(5)(b) again treating a non-account-payee instrument as cash.
Section 63(2) supplies the relief that makes the presumptive scheme attractive: audit does not apply where profits are declared in accordance with section 58(2). Staying at or above the deemed figure keeps a freelancer out of audit entirely, whatever the receipts, up to the scheme’s own ceiling. The specified date for the audit report is set by section 63(5)(a) as one month before the return due date.
What the rules do not yet settle is which books a specified profession must keep. The old regime prescribed that in rule 6F of the 1962 Rules, and the equivalent provision under the Income-tax Rules, 2026 is not established, so the requirement is clear while its contents are not.
The 50% is a floor, not an election. Where actual profit is higher, the higher figure is charged. Income-tax Act, 2025, sections 58, 62, 63 and 408, as amended by the Finance Act, 2026. Income Tax Department, accessed September 2026.
Choosing between the two tax regimes
The section 202 regime applies by default, and the older regime now has to be claimed inside the return. Section 202(1) applies its rates to an individual “unless the person exercises the option in the manner provided under sub-section (4)”, which reverses the burden that existed when the concessional regime was introduced.
The slab table in section 202(1) runs: nil up to Rs 4,00,000; 5% from Rs 4,00,001 to Rs 8,00,000; 10% to Rs 12,00,000; 15% to Rs 16,00,000; 20% to Rs 20,00,000; 25% to Rs 24,00,000; and 30% above that. Surcharge and the 4% health and education cess continue to come from the annual Finance Act rather than from the Act itself.
Section 156 carries the rebate. Sub-section (2)(a) allows the lower of the full tax payable or Rs 60,000 where income taxed under section 202(1) does not exceed Rs 12,00,000, with marginal relief in clause (b) for income just above that line. Sub-section (1) keeps the older regime’s rebate at the lower of full tax or Rs 12,500 up to Rs 5,00,000. Sub-section (3) then caps the rebate at tax payable at section 202(1) rates, so it does not erase tax charged at special rates on capital gains.
The widely circulated claim that Rs 12.75 lakh of income is tax-free under the new regime does not apply to a freelancer, and the reason is structural. Section 19 is headed “Deductions from salaries” and opens by computing “the income chargeable under the head ‘Salaries'”. The standard deduction of Rs 75,000 is an entry in its table, so it reduces salary and nothing else.
A freelancer with no salary component therefore gets nothing from it. The correct break-even for professional income is the Rs 12,00,000 rebate ceiling in section 156(2)(a), not Rs 12,75,000. That is a conclusion drawn from the two provisions rather than a figure either of them states, and it is worth checking against a specific set of numbers before relying on it.
The mechanics of claiming the older regime changed, and this is the point on which current guidance is most uniformly out of date. Rule 136 of the Income-tax Rules, 2026 provides that the option under the listed provisions “shall be in the return of income to be furnished under section 263(1) for such tax year”, and entry 4 in its table is section 202(4), against individuals, Hindu undivided families, associations of persons, bodies of individuals and artificial juridical persons.
The option is therefore exercised inside the return itself. There is no separate form, and Form 10-IEA has no successor anywhere in the department’s own mapping of forms from the 1962 Rules to the 2026 Rules. Guidance still instructing freelancers to file Form 10-IEA before the return is describing a procedure that no longer exists.
Section 202(4) sets out what the choice costs. For a person with business or professional income the option must be exercised on or before the due date under section 263(1); once exercised “shall apply to subsequent tax years”; “may be withdrawn only once for a tax year other than the tax year for which it was exercised”; and after that withdrawal the person “shall never be eligible to exercise the option under this sub-section” while business or professional income continues. Two moves, and then the door closes for as long as the freelancing does.
Section 202(2) disallows Chapter VIII in its entirety apart from sections 124(1), 124(2), 125(2) and 146, along with listed entries in Schedule III. In practical terms the life insurance and provident fund deduction that used to be section 80C is now section 123 read with Schedule XV and is unavailable; health insurance under old section 80D is section 126 and is unavailable; the additional pension contribution under old section 80CCD(1B) is section 124 and goes the same way. House rent allowance and leave travel allowance, both Schedule III entries, go too, though neither was available against professional income in the first place.
What survives is the part that matters most to a freelancer, and no published guidance appears to say so plainly. Section 202(2) operates on the computation of total income. The presumptive scheme in section 58 and the expense deductions in sections 26 to 36 operate before that point, in arriving at profits and gains of business or profession, and they are not Chapter VIII deductions. Neither route is touched by the default regime.
That is the mechanic which usually makes the default regime the cheaper one for a self-employed reader. A salaried taxpayer choosing the default regime gives up genuine deductions. A freelancer choosing it gives up a list of deductions that a presumptive computation had already made irrelevant, while keeping the deemed-profit rule or the expense claim intact. The comparison still has to be run on real numbers, and a freelancer with a large home loan or heavy insurance commitments may well land the other way.
One transitional question is unresolved. Whether an old-regime election already made under the 1961 Act carries into tax year 2026-27 or has to be exercised afresh is not established by any instrument located for this article, and it should be confirmed before the first return under the new Act is filed.
TDS, advance tax and the return
Three separate clocks run across a freelancer’s tax year, operated by three different parties: clients deducting at source through the year, the freelancer paying advance tax on fixed dates, and the return reconciling both after the year closes.
TDS on freelance fees and the refund problem
Deduction at source is now one section. Section 393 absorbed the whole of the 1961 Act’s Chapter XVII-B, including 194J, 194-O and 194M, with the rates and thresholds set out in tables rather than in separate provisions. The Press Information Bureau described the change as provisions that “have now been streamlined and grouped under a single section”, and it is the clearest illustration of why an old section number now dates a page rather than merely aging it.
The entries that catch freelance income sit at Table Sl. No. 6 and 8 of section 393(1).
Professional fees paid by a specified person, which covers companies and businesses above the turnover limits, fall under entry 6(iii) at 10%, once payments for the year cross a threshold of Rs 50,000. The 2% rate in the same entry is confined to technical services that are not professional services, film royalties and call centre operators, so a freelancer billing an Indian company should expect 10%. Where the payer is an individual or a Hindu undivided family, entry 6(ii) applies at 2% with a threshold of Rs 50 lakh, which in practice means most individual clients deduct nothing. Section 393(4) Table Sl. No. 9 removes the obligation altogether where an individual pays “exclusively for personal purposes”.
Platform payments run differently again. An e-commerce operator deducts under entry 8(v) at 0.1% of the gross amount with no threshold in the rate table itself. The familiar Rs 5 lakh relief sits separately in section 393(4), and it is conditional on three cumulative requirements, the third being that the participant has furnished a PAN or Aadhaar to the operator. Missing that condition removes the exemption entirely rather than reducing it.
Failing to furnish a valid PAN has a sharper consequence under section 397(2)(b), which substitutes the higher of the specified rate or 20%. For professional fees that turns a 10% deduction into 20%.
The arithmetic that follows is the most useful thing in this section, and it is absent from essentially every commercial guide on the topic. Tax is deducted at 10% of gross receipts. Tax is actually charged on the deemed profit, which for a specified profession is half of gross receipts, at slab rates that start at nil.
A consultant with Rs 18 lakh of receipts from Indian companies has Rs 1,80,000 deducted across the year. Presumptive income is Rs 9 lakh, on which the section 202(1) liability before cess is Rs 30,000, and the section 156(2) rebate extinguishes it entirely. The whole Rs 1,80,000 comes back as a refund, months later.
That is not a quirk of one figure. Running the same comparison across the whole professional scheme, with every client a specified person and no other income in the picture, the 10% deduction exceeds the actual liability at every level of receipts the scheme allows. At Rs 30 lakh of receipts the excess is about Rs 1.9 lakh, at Rs 50 lakh about Rs 1.57 lakh, and it narrows to roughly Rs 17,000 only at the Rs 75 lakh ceiling.
A freelancer inside the presumptive scheme is therefore lending money to the government for most of the year, by design rather than by mistake. The statutory answer is section 395(1), which allows a payee to apply for deduction “at a lower rate or no deduction of income-tax”, and obliges the payer to follow the resulting certificate. The application is made on Form 128, the successor to Form 13, and section 395(6) adds an electronic route under which a prescribed authority may issue or reject the certificate on electronic verification. Section 395 is also drafted more broadly than the old section 197, opening on any sum on which tax is deductible under the chapter rather than a closed list of provisions.
The self-declaration route is not an alternative here. Section 393(6), with Form 121 replacing Forms 15G and 15H, lists provident fund balances, insurance commission, rent, units and interest. Professional fees are not among them, so Form 128 is the only route available to a freelancer.
Where a client deducts but never deposits, section 401 is the protection: “Where tax is deductible at the source under this Chapter, the assessee shall not be called upon to pay the tax himself to the extent to which tax has been deducted from that income.” Credit itself flows from section 390(5), which treats deducted tax as paid on the deductee’s behalf. Two form numbers changed here as well, and both are checked constantly: the annual information statement that used to be Form 26AS is now Form 168, and the non-salary deduction certificate that used to be Form 16A is now Form 131.
Advance tax and the single March instalment
Advance tax is payable once the liability for the year, after reducing tax deducted at source, reaches Rs 10,000, under section 404. Section 408(1) then sets four instalments: 15% by 15 June, 45% by 15 September, 75% by 15 December and the whole amount by 15 March.
Freelancers inside the presumptive scheme are on a different schedule, and section 408(2) states it directly: “An assessee, who declares profits and gains as per the provisions of section 58(2) (Table: Sl. No. 1 or 3), shall pay the whole amount of advance tax on the current income … on or before the 15th March.” Both presumptive rows qualify, the business row as much as the professional one, so an unlisted trade using the 6% and 8% scheme gets the same single date. Section 408(3) adds that anything paid by 31 March still counts as advance tax for that year.
Interest for missing instalments is section 425, and the statute expresses it as flat percentages of the shortfall rather than as a monthly rate: 3% at each of the first three dates and 1% at 15 March. Section 425(2) provides two tolerances that reward approximate payment, with no interest arising if at least 12% is paid by 15 June or at least 36% by 15 September. Section 425(3) carves out the presumptive assessee, which is the logical consequence of having only one date to miss. Separately, section 424 charges interest where advance tax paid falls below 90% of assessed tax.
The gap between the two schedules is therefore larger than it appears. A freelancer on actual expenses who underpays in June carries interest across three quarters. A freelancer on presumptive income has a single exposure, at 1%, and only if the whole amount is not paid by 15 March.
Due dates come from the table in section 263(1)(c). A person whose accounts require audit files by 31 October. A transfer pricing report case files by 30 November. Everyone else, including a non-audit freelancer, falls into entry 5, “Any other assessee”, with a due date of 31 July.
There is no 31 August entry in section 263. That date is circulating on several ranking pages as the due date for non-audit business and professional filers, and it comes from a Central Board of Direct Taxes extension issued for assessment year 2026-27 under the 1961 Act. It belongs to a different year and a different statute, and reading it into the 2025 Act produces a deadline that does not exist.
Section 263(1)(a)(ix) adds an obligation that applies regardless of income. A resident who at any time in the tax year holds an asset outside India, including a financial interest in an entity, or has signing authority over any account outside India, must file a return. Freelancers holding balances with foreign payment providers are inside that provision even in a year they earn little, and the mechanics of those receipts are set out in our guide to receiving international payments in India as a consultant.
Cross-border relief carries new numbers too. Treaty relief is section 159, whose sub-section (4) preserves the long-standing rule that the Act applies “to the extent they are more beneficial to that assessee”. Section 160 handles countries with no agreement, giving credit at the Indian rate or the foreign rate, whichever is lower.
The form for claiming foreign tax credit, long known as Form 67, is now Form 44 under rule 76 of the Income-tax Rules, 2026, a change absent from every ranking commercial page checked for this article. Freelancers billing US clients face a related set of withholding questions covered in our note on the 1099 threshold and what it means for freelancers earning from US clients.
One thing cannot be stated yet. Return forms for tax year 2026-27 had not been notified as at the end of September 2026. The ITR-1 to ITR-7 series notified in March 2026 belongs to assessment year 2026-27 under the 1961 Act, which is a different year under a different statute, so any guidance naming ITR-3 or ITR-4 for the first year of the new Act is describing forms that do not exist yet.
Late filing is section 428, which replaced the old section 234F and kept its amounts: Rs 1,000 where total income does not exceed Rs 5,00,000, and Rs 5,000 in any other case.
FAQs
Does a freelancer earning under Rs 20 lakh from foreign clients need to register for GST?
Registration turns on aggregate turnover crossing Rs 20 lakh for a supplier of services under section 22 of the Central Goods and Services Tax Act, 2017, or Rs 10 lakh in the four special category states. The Rs 40 lakh figure often quoted comes from a 2019 notification limited to an exclusive supplier of goods and has never applied to a freelancer. Export of services is zero-rated, and Notification 10/2017-Integrated Tax exempts sub-threshold inter-state suppliers of services from registration, so nothing compels it by itself, though a letter of undertaking or a refund is available only to a registered person. Presumptive taxation under the Income Tax Act has no bearing on the question, since the GST test looks only at aggregate turnover.
Does the section a client deducts tax under decide which scheme a freelancer can use?
The deduction provision and the computation provision operate independently of each other. A client deducting under section 393(1) Table Sl. No. 6(iii) is complying with its own obligation and is making no statement about the freelancer’s eligibility, which section 62(4) and the receipts ceiling in section 58 decide. Mismatches between the two do cause processing queries in practice, so the presumptive row claimed in the return should be the one the statute supports rather than the one implied by the client’s deduction.
What happens when a client deducts tax but it never appears in the annual information statement?
Section 401 bars a direct demand on the assessee to the extent tax has been deducted from that income, so the deduction itself protects the freelancer even where the client has not deposited it. Credit in the statement follows the deductor filing its quarterly statement, and correction statements remain possible for two years from the end of the tax year in which the original was due. The practical route is to hold the deduction certificate, now Form 131, and pursue the deductor.
Is the 50% under section 58 a ceiling or a floor?
Column E of Table Sl. No. 3 charges “50% of the gross receipts or profit claimed to have been actually earned, whichever is higher”, which makes the figure a floor rather than a ceiling. A freelancer whose real profit exceeds half of receipts declares the real figure. Declaring below the deemed figure is possible, but under section 58(3) it brings books under section 62 and audit under section 63 once total income exceeds the amount not chargeable to tax.
References
Income-tax Act, 2025 and the Income-tax Rules, 2026
- Section 58, special provision for computing profits and gains of business or profession on presumptive basis in case of certain residents. Income Tax Department, Income-tax Act, 2025 as amended by the Finance Act, 2026
- Section 202, new tax regime for individuals, Hindu undivided family and others. Income Tax Department
- Section 393, tax to be deducted at source. Income Tax Department
- Utility to check provisions of Income-tax Act, 1961 vis-a-vis Income-tax Act, 2025. Income Tax Department
- Sections 1, 3, 4, 6, 19, 26 to 36, 62, 63, 156, 159, 160, 263, 390, 395, 397, 401, 403 to 408, 423 to 425, 428 and 536, Income-tax Act, 2025. Income Tax Department bare Act pages
- Rule 25 and Appendix I, and rules 76 and 136, Income-tax Rules, 2026. Income Tax Department
- The Income-tax Act, 2025 (Act No. 30 of 2025), assented 21 August 2025. Gazette of India, Extraordinary, Part II Section 1
Goods and services tax
- Section 22 and section 24, Central Goods and Services Tax Act, 2017, and section 2(6) and section 16, Integrated Goods and Services Tax Act, 2017. Central Board of Indirect Taxes and Customs
- Notification No. 10/2017-Integrated Tax and Notification No. 10/2019-Central Tax. Central Board of Indirect Taxes and Customs
Official commentary
- “The Income Tax Act, 2025: Reshaping Tax Framework”, 3 September 2025. Press Information Bureau
- Forms mapping, Income-tax Rules, 1962 vis-a-vis Income-tax Rules, 2026. Income Tax Department
This article is for informational and educational purposes only and does not constitute professional, financial, legal or tax advice. Tax positions depend on individual facts, and several points noted above remain unsettled. Readers should consult a qualified tax professional before acting on any of it.


 Allow notifications