
 US
 IN
 UK


 Duration - 6 Month, 12-15 hours/week
 Course fee: - INR 1,55,000 + GST
About the Collaboration: iHUB, DivyaSampark IIT Roorkee & SkillArbitrage
Certification
Transform Your Career with Quantitative Finance & Trading Systems Skills
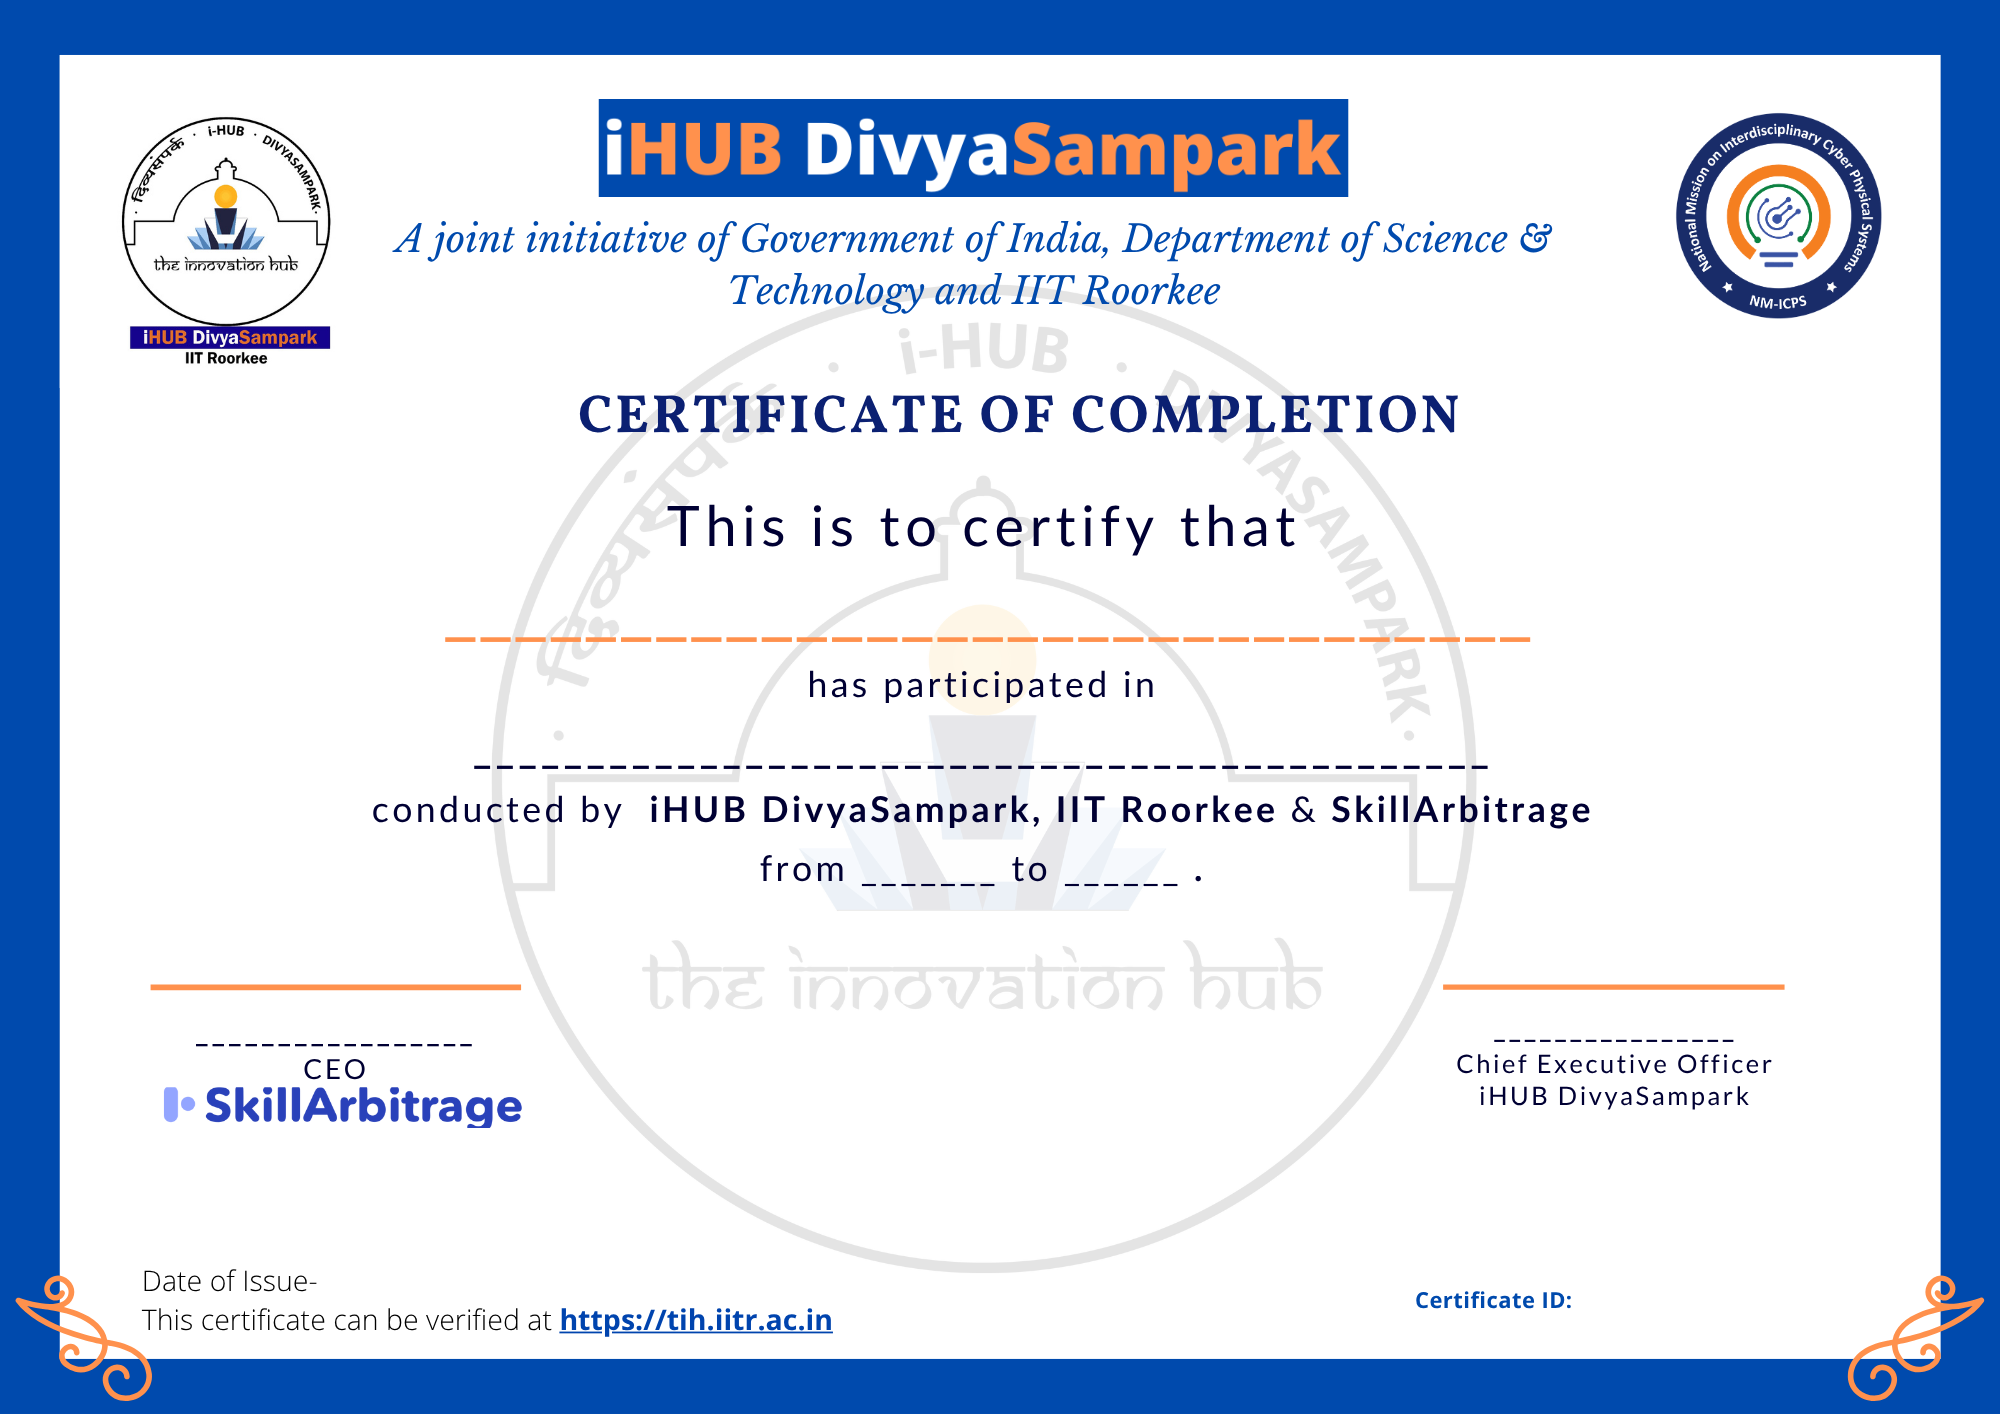
Participants who successfully complete the program will receive a co-branded certificate from SkillArbitrage and iHUB DivyaSampark, IIT Roorkee.
The Finance Industry is Being Transformed by Quantitative Methods
- Source, clean, and query financial data fluently in Python and SQL — handling the messy reality of missing ticks, survivorship bias, and broken feeds
- Build and honestly evaluate trading strategies with proper transaction costs, slippage, out-of-sample testing, and overfitting controls
- Price derivatives using stochastic calculus, Monte Carlo simulation, and PDE methods — and validate the models rigorously
- Measure and manage risk using VaR, Expected Shortfall, and regulatory frameworks (FRTB, Basel III/IV)
- Apply machine learning to finance with temporal cross-validation, leakage prevention, and explainability — not just raw accuracy
- Build low-latency systems in modern C++ for trading infrastructure, matching engines, and feed handlers
Who Should Take This Course?
This course is designed for ambitious individuals who want to build genuine, employer-relevant quantitative finance skills — the mathematics, programming, and judgment the work actually requires.
Software Engineers & Developers
Programmers with strong Python or C++ skills who want to enter quantitative finance. You already know how to build systems — this program adds the financial mathematics, market knowledge, strategy design, and risk management that transform a developer into a quant developer. The Developer track takes you deep into modern C++, systems programming, and matching-engine architecture.
Finance Professionals & Traders
CAs, CFAs, MBAs, and working finance professionals who understand markets but want to build quantitative and programming skills. Move beyond spreadsheets into Python-based analysis, systematic strategy development, and model-driven decision making. The Risk and Analytics tracks are particularly well-suited to your existing domain expertise.
Data Scientists & ML Engineers
Professionals with strong machine-learning and statistics backgrounds who want to apply their skills to finance. Learn the domain-specific pitfalls — look-ahead bias, overfitting to noise, survivorship bias — that make financial ML fundamentally different from typical data science, and build models that survive contact with real markets.
Quantitative Aspirants & IIT/NIT Graduates
Engineering and mathematics graduates targeting quant roles at trading firms, hedge funds, banks, and fintech companies. This program builds the specific combination of skills — programming + mathematics + markets + portfolio — that quant employers test for in their technical interviews.
Fresh Graduates & Students
B.Tech, M.Tech, M.Sc., MBA students or recent graduates in engineering, mathematics, statistics, economics, or computer science who want to build a career in quantitative finance. Enter the job market with a skill set, a portfolio of working projects, and a professional credential that most candidates lack.
Career Switchers with Analytical Backgrounds
Actuaries, statisticians, risk analysts, or anyone with strong quantitative foundations looking to pivot into quant finance. Your mathematical and analytical skills are the hardest part to teach — this program adds the market knowledge, programming tools, and industry-specific techniques.
What Will You Learn in This Course
By the end of this 6-month program, you will not only understand quantitative finance concepts but also know how to implement them — building working systems, validated models, and honest strategy evaluations using the tools and techniques that real quant teams rely on.
You will learn to:
- Set up a professional quant workstation with Anaconda, VS Code, Git, and build a reusable financial-data toolkit using pandas and NumPy for sourcing and cleaning Indian and US market data.
- Query financial databases fluently in SQL — joins, window functions, and aggregation over time-series and transactional data, a foundational skill assumed across all quant and analytics work.
- Master the mathematics and statistics for quant work — probability, distributions, expectation/variance, linear algebra, hypothesis testing, and estimation to genuine working competence.
- Build leakage-proof time-series pipelines — stationarity, returns, autocorrelation, correct temporal train/test splitting, and the no-look-ahead discipline that separates professional work from amateur backtests.
- Understand markets, instruments & microstructure — equities, futures, options, the Greeks, order books, market-making basics, and how Indian (NSE/BSE) and global exchanges actually operate.
- Solve data-structures and algorithms problems at the level required for quant technical assessments — complexity analysis, arrays, maps, trees, graphs, recursion, and core problem-solving patterns.
- Backtest trading strategies honestly — event-driven architecture, transaction costs, slippage, realistic fills, in-sample vs out-of-sample evaluation, walk-forward validation, and rigorous overfitting controls.
- Build risk and portfolio analytics — VaR, Expected Shortfall, Sharpe ratio, drawdown analysis, volatility modelling, position sizing, correlation, and portfolio construction.
- Apply machine learning to finance correctly — framing finance problems as ML, feature engineering, temporal cross-validation, and evaluating on the right metrics (not raw accuracy).
- Build explainable ML models using Random Forest, gradient boosting, and SHAP — and defend your model's decisions with rigorous reasoning.
- Specialise in one of three deep tracks:
Track A — Quant Developer:
- Write modern C++ (types, memory, RAII, STL, templates, concurrency, lock-free, profiling)
- Master systems programming — Linux/OS internals, networking (TCP/UDP/multicast), low-latency techniques
- Build a matching engine and market-data feed handler; learn kdb+/q for tick data
Track B — Quant Risk & Validation:- Apply stochastic calculus — Itô, Black-Scholes, the Greeks; rate & vol model families (Hull-White/HJM, Heston/SABR/Dupire)
- Implement numerical methods — Monte Carlo (Euler/Milstein), PDE/finite-difference, trees
- Master regulatory risk — FRTB, Basel III/IV, VaR→ES, CVA/XVA; credit risk (PD/LGD/EAD, scorecards)
- Build and validate a pricer + VaR/ES engine (FRM-aligned)
Track C — Quant Analytics / Data Science:- Build advanced ML models for credit-risk and fraud detection
- Research alpha signals using time-series ML and alternative data
- Apply NLP and FinBERT for financial sentiment analysis; build dashboards
- Containerise and deploy analytics capstones (Docker + cloud basics
-
Solve quantitative aptitude problems at interview standard — probability, expected value, Bayes, game theory, and rapid mental-math practice.
-
Run live market-making simulations — rapid options/Greeks reasoning and structured decision-making under uncertainty.
-
Build a public technical record — competitive-programming practice (Codeforces), submitting research to WorldQuant BRAIN, and open-source contributions as verifiable evidence of ability.
-
Design and present a substantial capstone project — a matching engine/feed handler (Developer), a pricer + VaR-ES validation (Risk), or a credit-risk model + clean backtest (Analytics) — with AI/data tools integrated.
-
Prepare for technical interviews — practice the specific format used by quant firms: mental-math + live C++/Python problem-solving, and build a published, documented portfolio.
Super 30: Real-World Quantitative Finance Tasks You Can Master and Perform Like a Pro
- Source, clean, and normalise financial data from Indian (NSE/BSE) and global markets using Python and pandas.
- Write complex SQL queries over time-series and transactional financial databases with window functions and aggregation.
- Solve probability, statistics, and linear algebra problems to genuine working competence — not just textbook exercises.
- Build leakage-proof time-series pipelines with correct temporal splitting and the no-look-ahead discipline.
- Analyse market microstructure — order books, price formation, liquidity dynamics, and venue mechanics.
- Solve data-structures and algorithms problems at the level expected in quant technical assessments.
- Design and implement systematic trading strategies with clear hypothesis, entry/exit logic, and position sizing.
- Build an event-driven backtester with realistic transaction costs, slippage, and fill modelling.
- Evaluate strategies rigorously using in-sample/out-of-sample testing, walk-forward analysis, and purged cross-validation.
- Detect and eliminate overfitting, survivorship bias, and look-ahead bias in strategy research.
- Generate professional strategy tear sheets with risk-adjusted metrics (Sharpe, Sortino, Calmar, max drawdown).
- Make disciplined go/no-go deployment decisions based on quantitative evidence, not gut feel.
- Calculate Value-at-Risk and Expected Shortfall using parametric, historical, and Monte Carlo methods.
- Price options and derivatives using Black-Scholes, binomial trees, and Monte Carlo simulation.
- Build and validate a VaR/ES risk engine aligned with regulatory frameworks (FRTB, Basel III/IV).
- Construct and optimise portfolios with proper correlation analysis, position sizing, and risk budgeting.
- Model credit risk using PD/LGD/EAD frameworks and build credit scorecards.
- Compute and interpret the Greeks for options hedging and risk management.
- Frame financial prediction problems as properly structured ML tasks with correct temporal validation.
- Build and defend explainable ML models using Random Forest, gradient boosting, and SHAP.
- Research alpha signals using time-series ML with proper feature engineering and leakage control.
- Apply NLP and FinBERT for financial sentiment analysis on earnings calls, filings, and news.
- Build credit-risk and fraud-detection models with real-world class-imbalance handling.
- Use LLM-assisted research and RAG over financial documents and filings.
- Write performance-conscious modern C++ for trading infrastructure — types, memory, concurrency, and profiling.
- Build trading-system components: a matching engine, feed handler, and market-data parser.
- Solve quantitative brainteasers, probability puzzles, and mental-math challenges at interview speed.
- Run live market-making simulations with rapid options reasoning and decision-making under uncertainty.
- Containerise and deploy financial analytics applications using Docker and cloud basics.
- Present and defend a complete capstone project with architecture documentation, a professional README, and a live demo
By mastering these skills, you'll transform from someone who reads about quantitative finance to someone who builds and deploys quantitative systems. You'll hold the combination of mathematics, programming, and market knowledge that defines the most valuable professionals in modern finance.
Syllabus
Phase 1: Common Core — Foundations (Weeks 1–10) 
 Week 1: Quant Workstation & Python for Financial Data — Anaconda/VS Code/Git; pandas & NumPy; sourcing & cleaning Indian + US market and fundamental data; building a reusable data layer
Week 2: SQL for Finance — Queries, joins, window functions and aggregation over time-series and transactional financial data
Week 3: Mathematics & Statistics for Quant — Probability, distributions, expectation/variance, linear algebra, hypothesis testing and estimation
Week 4: Time-Series & the No-Look-Ahead Discipline — Stationarity, returns, autocorrelation, resampling; correct temporal train/test splitting and leakage prevention
Week 5: Markets, Instruments & Microstructure — Equities, futures & options, the Greeks, order books, market-making basics, and how Indian (NSE/BSE) and global exchanges operate
Week 6: Data Structures & Algorithms — Complexity, arrays/maps/trees/graphs, recursion and core problem-solving patterns for quant technical assessments
Week 7: Backtesting Done Honestly — Event-driven backtester architecture; transaction costs, slippage, realistic fills; in-sample vs out-of-sample, walk-forward and purged cross-validation; overfittin
Week 8: Risk & Portfolio Foundations — VaR, Expected Shortfall, Sharpe, drawdown, volatility, position sizing, correlation and basic portfolio construction
Week 9: Applied Machine Learning for Finance I — Framing finance problems as ML; regression & classification; feature engineering; temporal cross-validation
Week 10: Applied ML for Finance II + the AI/Data Spine — Random Forest, gradient boosting, SHAP explainability; reasoning about and defending a model; introduction to the AI/data spine
Phase 2: Specialisation Tracks — Go Deep on One (Weeks 11–18)
Track A — Quant Developer
Track B — Quant Risk & Validation
Track C — Quant Analytics / Data Science
Phase 3: Aptitude, Signal-Building & Capstone (Weeks 19–24)
The skills and the body of work that demonstrate genuine competence — quantitative aptitude, a public technical record, and a substantial capstone.
-
Week 19: Quantitative Aptitude I — Probability / expected-value / Bayes / game-theory problem-solving; rapid mental-math practice — the reasoning core of quant technical assessmentsWeek 20: Quantitative Aptitude II — Market-Making Lab — Live market-making simulation exercises; rapid options/Greeks reasoning; structured decision-making under uncertaintyWeek 21: Building a Public Technical Record — Competitive-programming practice (Codeforces); submitting real research to WorldQuant BRAIN; open-source contribution — verifiable, skill-based evidence of abilityWeek 22: Capstone Build (Deep in Your Track) — A matching engine / feed handler (Dev), a pricer + VaR-ES validation (Risk), or a credit-risk model + clean backtest (Analytics) — with AI/data spine integratedWeek 23: Portfolio, Credentials & Compliance Literacy — GitHub portfolio, README, architecture diagram, demo; FRM / CQF study pathways; SEBI's 2025 retail-algorithmic-trading framework complianceWeek 24: Technical-Interview Practice & Portfolio Launch — Practice technical interviews (mental-math + live C++/Python problem-solving) to consolidate skills; finalize and publish portfolio
Training Methodology

Online 24/7 access
Access study materials via our online portal & via our Android & iOS apps—learn at your own pace, on your own schedule.

Practical Exercises
One assignment including two practical exercises every week
Optional Campus Interaction
Optional Campus Immersion at IIT Roorkee Campus

Convenient Class Timings
Classes are held after work hours, typically on Sundays or after 8 PM on weekdays—perfect for working professionals and students.

Live Online Classes
Live online classes based on exercises, allowing questions, discussions, and real-time feedback with instructors.

Industry-Standard Tools
Hands-on training in ChatGPT, Claude, Python, Excel, Power BI, Tally integration, OCR tools, and no-code automation platforms used by finance professionals worldwide.

Live Doubt Clearing
One-on-one sessions with mentors and instructors to ensure you never feel stuck or confused.
Three Specialisation Tracks
Career Potential After This Course
Career Roles You Can Pursue
- Quant Developer — Build trading infrastructure, matching engines, feed handlers, and low-latency systems at proprietary trading firms, hedge funds, and exchanges.
- Quant Researcher / Quantitative Analyst — Research alpha signals, build predictive models, and develop systematic trading strategies for asset managers and hedge funds.
- Quant Risk Analyst / Model Validator — Price derivatives, validate risk models, and implement regulatory risk frameworks (FRTB, Basel III/IV) at banks and financial institutions.
- Algorithmic Trader / Systematic Trader — Design, backtest, and deploy data-driven trading strategies across equities, futures, options, and FX markets.
- Finance Data Scientist — Apply machine learning to credit risk, fraud detection, sentiment analysis, and financial forecasting at banks, fintechs, and asset managers.
- Quantitative Portfolio Manager — Construct and manage systematic portfolios with proper risk budgeting, position sizing, and performance attribution.
- Credit Risk Modeller — Build PD/LGD/EAD models, credit scorecards, and regulatory capital models for banks and NBFCs.
- Execution Algorithm Developer — Design smart execution and order-routing algorithms for buy-side and sell-side institutions.
- Fintech / Capital Markets Engineer — Build analytics platforms, risk systems, and data infrastructure at fintech companies serving the financial industry.
- Independent Quantitative Researcher — Develop and deploy your own systematic strategies with proper backtesting discipline, risk controls, and regulatory awareness.
Potential Employers and Opportunities
After completing this course, you can work with:
- Proprietary trading firms and market makers (Tower Research, Optiver, Graviton, AlphaGrep, NK Securities, etc.)
- Quantitative hedge funds and systematic asset managers
- Investment banks — quant desks, risk management, model validation, and electronic trading
- Stock exchanges and clearing houses (NSE, BSE, SGX, CME)
- Asset management companies and mutual funds with quantitative strategies
- Fintech companies building trading, risk, and analytics platforms
- Credit-rating agencies, NBFCs, and insurance companies with quantitative modelling teams
- Consulting firms specializing in financial risk and quantitative advisory
What Kind of Career Support Will I Get?
Placement, career, and recruitment support for this program is provided by SkillArbitrage and includes:
- Skill-First Approach: This program focuses on building genuine, demonstrable competence — the kind that speaks for itself in technical interviews and portfolio reviews.
- Portfolio & Technical Record: You graduate with a substantial, reviewed capstone project, a professional GitHub portfolio, a Codeforces profile, and WorldQuant BRAIN submissions — verifiable evidence of your skills that goes far beyond a certificate.
- Three Specialisation Pathways: Choose between Quant Developer, Quant Risk & Validation, or Quant Analytics/DS — each an 8-week deep dive that produces genuine specialist competence, not a surface-level overview.
- Interview Preparation: Dedicated preparation for quant technical interviews — probability puzzles, mental math, live coding (C++/Python), and market-making simulations — the specific format that top firms use.
- Career Guidance: Our dedicated team assists you with career planning, CV crafting, and professional positioning throughout your learning journey.
- Professional Credential Pathways: Guidance on next steps including FRM, CQF, and other professional certifications that complement and build on this program's skill set.
- Credential Value: A co-branded certificate from iHUB DivyaSampark, IIT Roorkee and SkillArbitrage — a unique credential combining IIT's research heritage with practical quantitative finance expertise.
All the services with respect to career support are provided solely by SkillArbitrage.
How Will You Clear My Doubts and Help Me If I Am Struggling?
Money-Back Guarantee
Faculty

Sonali Parashar,
Dy. Director - Finance & International Vertical


Vibhore Solanki,
Senior Associate, Lawsikho & SkillArbitrage
What Makes This Course Unique?
- Joint Certification by IIT Roorkee and SkillArbitrage: Get certified by one of India's premier technical institutions (IIT Roorkee) along with the country's leading skill development platform—a combination that adds immense credibility to your profile.
- Three Deep Specialisation Tracks: Unlike one-size-fits-all quant courses, this program lets you go genuinely deep in one of three tracks — Quant Developer, Quant Risk & Validation, or Quant Analytics/DS — while staying literate in all three. Depth is what makes the skill real.
- Skills-First, Rigour-First Design: Every concept is backed by working code and a reviewed project. No hand-waving, no toy examples — you build the systems that real quant teams build, with the same discipline they apply.
- Honest Backtesting & Anti-Overfitting Discipline: Most quant courses teach you to build strategies that look great on paper. This course teaches you why most backtests lie — and how to build the rare ones that don't. The no-look-ahead discipline runs through every week.
- AI/Data Spine Throughout: Machine learning isn't a bolt-on module — it runs through the entire program, from ML-based strategy research to LLM-assisted financial analysis and RAG over filings. This is why an IIT technology-innovation hub is the right home for this program.
- India-Specific Market & Regulatory Coverage: NSE/BSE data, Indian market microstructure, SEBI's algorithmic-trading and 2025 retail-algo framework — critical knowledge for anyone working in Indian capital markets.
- Quantitative Aptitude & Interview Preparation: Mental math, probability puzzles, market-making games, and live coding practice — the specific preparation for the notoriously rigorous quant interview process, integrated into the curriculum rather than left as an afterthought.
- Public Technical Record: You don't just build projects — you build a verifiable public footprint: Codeforces submissions, WorldQuant BRAIN research, open-source contributions, and a professional GitHub portfolio.
- Capstone Project: Design, build, and present a substantial project in your chosen track — a matching engine (Dev), a pricer + VaR engine (Risk), or a credit model + backtest (Analytics) — reviewed by instructors and demonstrating real competence.
- Pathway to Advanced Certifications: This program is designed as the foundation for further professional certifications (FRM, CQF) and serves as the on-ramp to our advanced Algorithmic & High-Frequency Trading companion program for those who want to go even deeper.
Course Plan
Standard
₹ 155000
incl. of all charges
Instructor-led course with online classes featuring AI tool demonstrations
Online assessments (flexible exam scheduling within given time slots)
1 online class per week
Practical case studies and assignments with hands-on AI tool implementation
Digital certificate (co-branded by iHub DivyaSampark, IIT Roorkee and SkillArbitrage)
Get digital access to entire study material including AI tool tutorials
Access on LMS, Android & iOS app
Live doubt clearing sessions covering academic writing concepts and AI tool usage
Placement assistance for internships, jobs and referrals highlighting AI proficiency
CV enhancement support emphasizing AI-enhanced academic writing expertise
Training for writing and publishing articles, making profiles and taking work on freelance platforms with AI tool showcase
Technical support for AI tool implementation throughout the program